All Categories
Featured

Estimating 2026 LTC Expenses
Table of Contents
Consist of real-life care situations: dementia, movement loss, single-spouse need. At home vs. center, household involvement, care quality. The finest time to plan for long-lasting care is when you do not require it.
serves as the Chief Financial Investment Officer at Langan Financial Group. In this function, he handles financial investment portfolios, acts as a fiduciary for group retirement plans, and seeks advice from customers concerning their financial objectives, threat tolerance, and asset allowance. With a focus on ERISA Law, Alex finished orgasm laude from Widener Commonwealth Law School.
Alex is also enthusiastic about returning to the neighborhood, and has taken part in The Structure of Enhancing Communities' Emerging Benefactor Program, volunteers at his church, and serves as a board member of Samara: The Center of Individual & Family Development. Outside of work and offering, Alex enjoys his time with his spouse Sarah, and their 3 kids, Rory, Patrick, and Ava.
Understanding Long-Term Care Insurance Versus Medicare
Your household's future. Langan Financial Group provides financial planning and investment management for people, households, and company owners. We assist you work through concerns about retirement income, investment decisions, Social Security, and how taxes may impact your financial plan.
From there, we assist you evaluate your choices and establish a plan that can develop as your life changes. We also help organizations and companies assess workplace retirement strategies and comprehend their obligations as plan sponsors.
Retirement Planning Huntington BeachThe opinions revealed and material provided are for general info, and ought to not be considered a solicitation for the purchase or sale of any security.
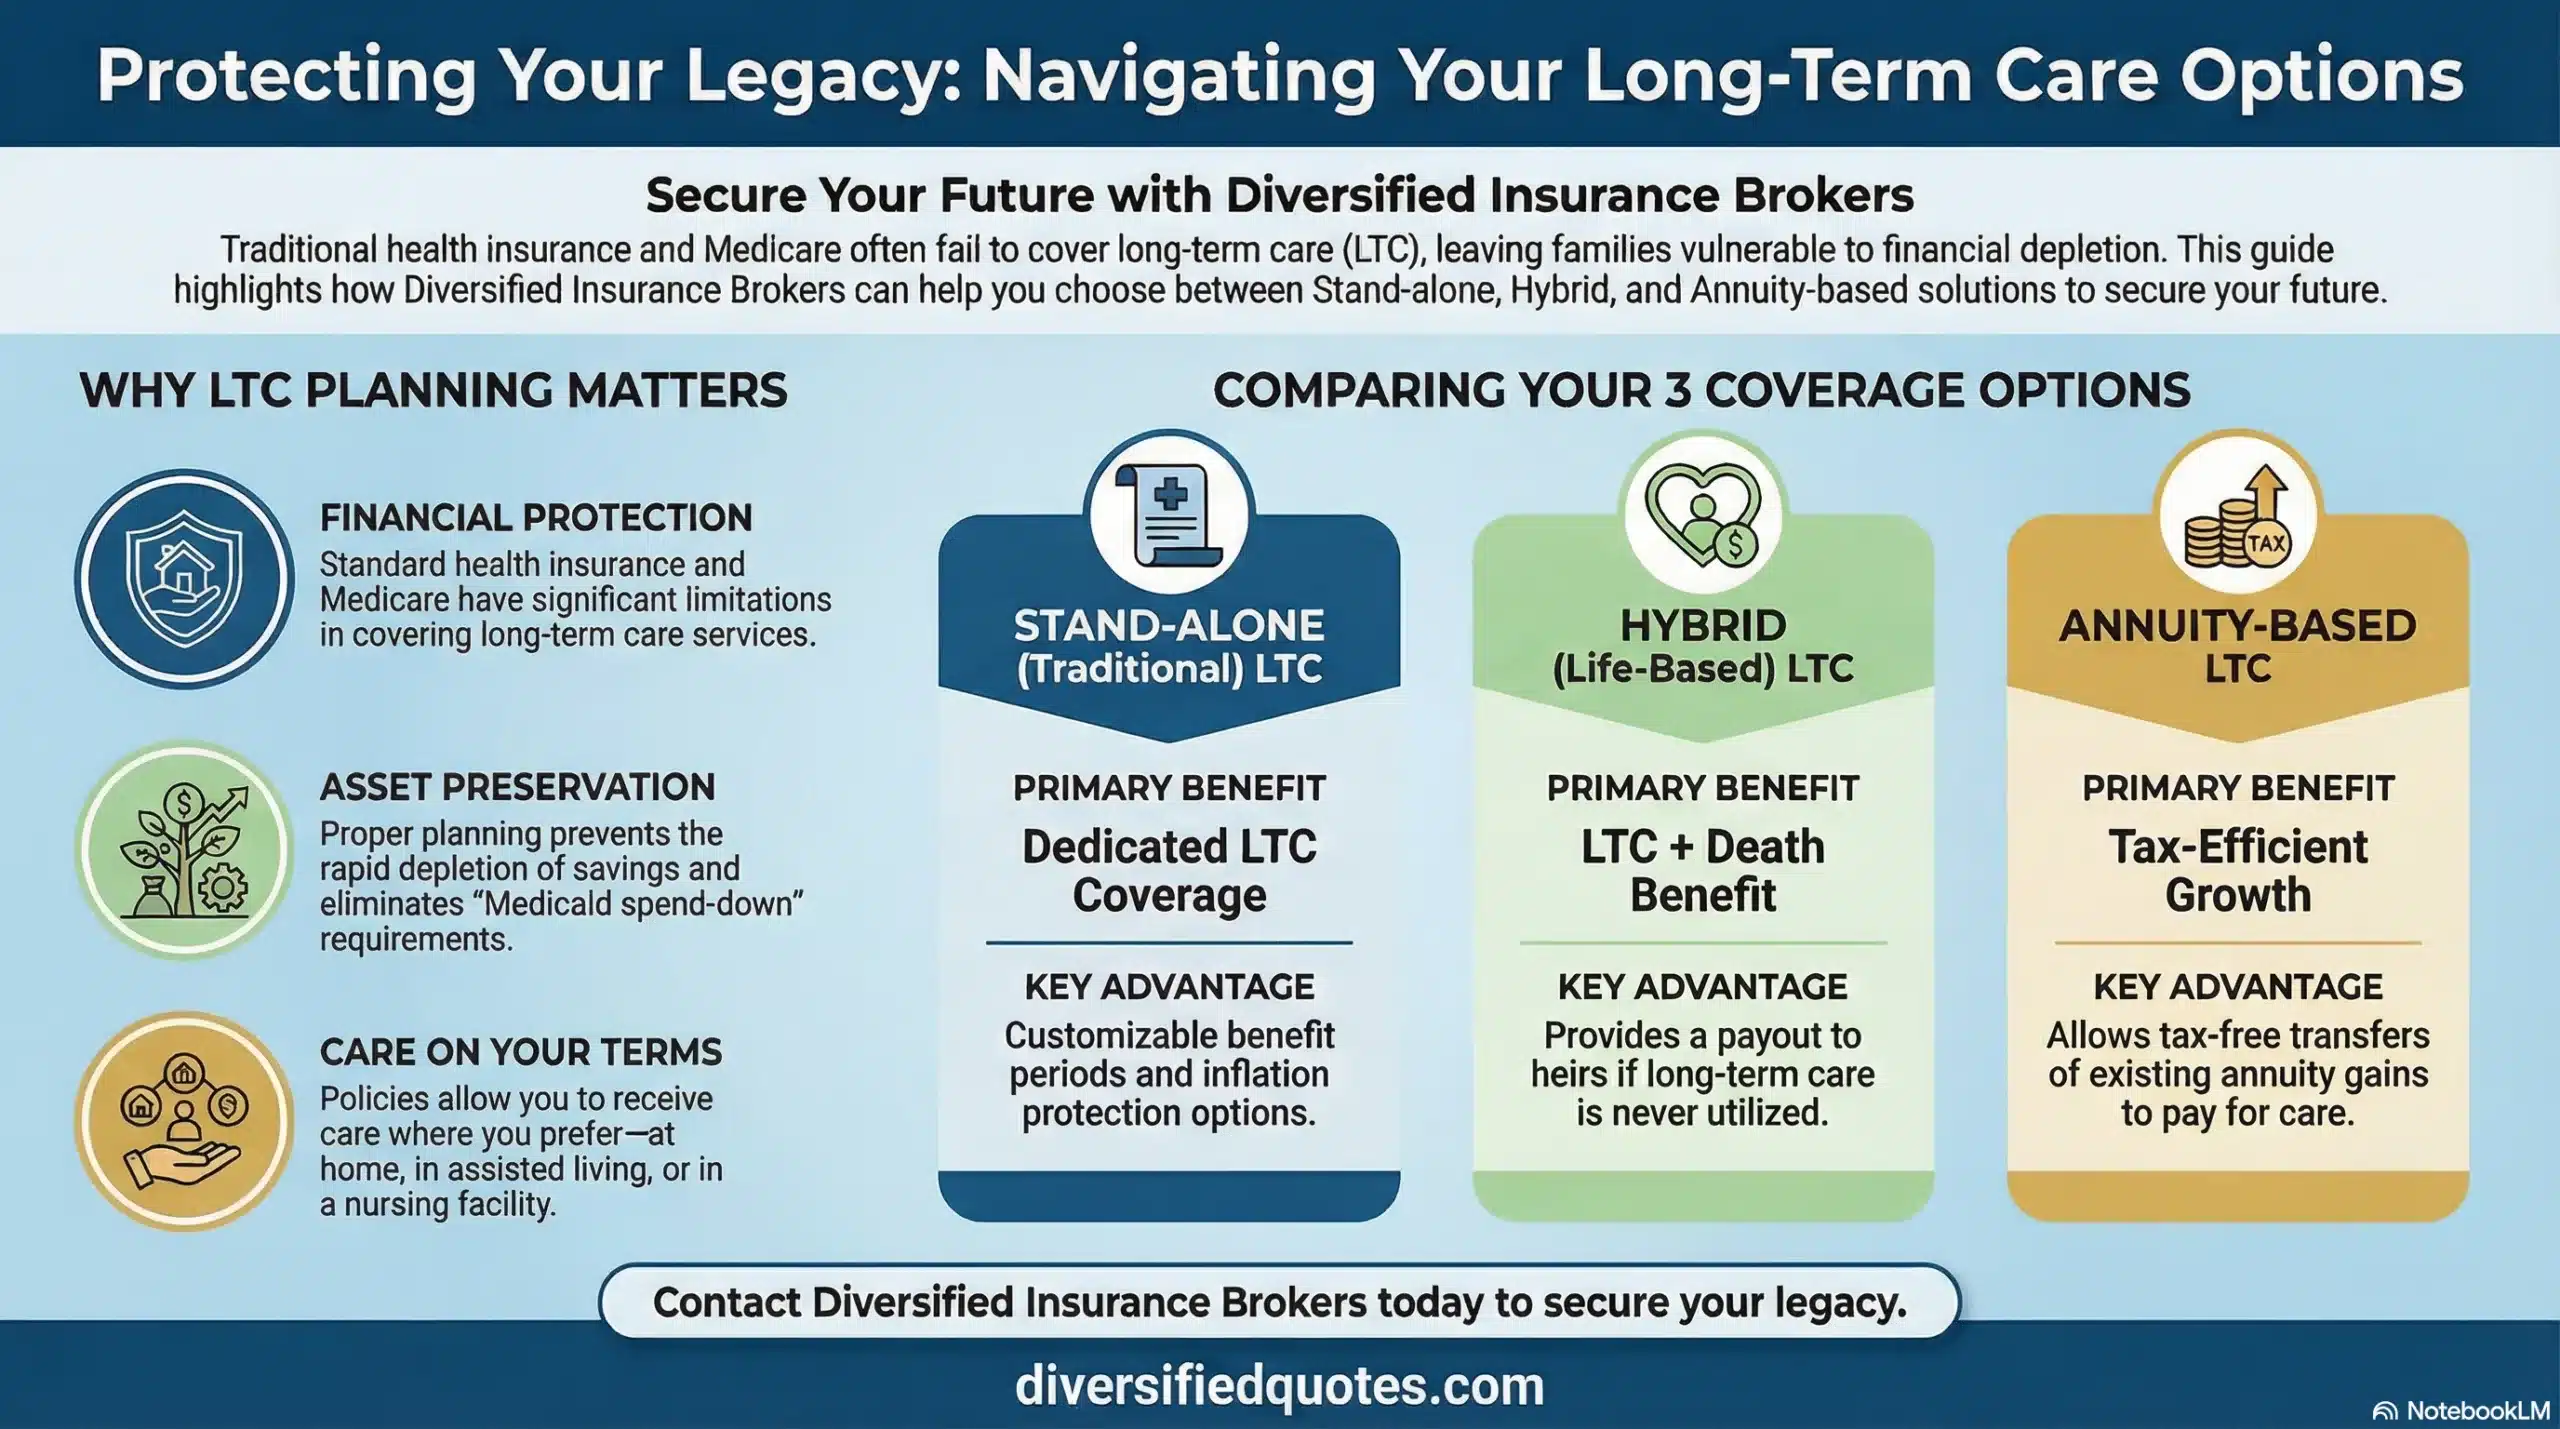
Most Americans erroneously believe Medicare will cover their long-term care needs in retirement. This critical misunderstanding can lead to devastating monetary consequences when care is ultimately required. Medicare supplies restricted coverage for long-term care services: Up to 100 days maximum Requires a certifying 3-day health center stay very first Days 21-100 need a daily copayment ($200+ per day in 2025) Should reveal continuous improvement to keep protection Restricted protection Needs physician certification of medical requirement Should be competent nursing care (not custodial) Care should be part-time or intermittent only the support with activities of day-to-day living that Medicare does not cover:.
Strategic Strategy for Elder Care in 2026
The relationship in between long-lasting care (LTC) and treatment covered by TRICARE, Medicare, or employer healthcare can be complicated. Examples of medical insurance include your health strategy at work, TRICARE or TRICARE for Life, and Medicare. These cover medical expenses related to the treatment of a sickness or injury.
After treatment, recovery or healing is not covered. It's about the need for assistance when you can't carry out regular activities of life and you need help to function.
Numerous people think of LTC as nursing home care. A better description would be stay-at-home care.
Navigating Rising Care Rates in 2026
Many Americans wrongly believe Medicare will cover their long-term care requirements in retirement. This critical misconception can lead to devastating monetary consequences when care is eventually required.
While it may be tough to think of now, it's likely that you'll require some kind of health care or everyday living assistance as you age. Individuals often believe that Medicare covers long-lasting care, either in the house or in a nursing facility, however unfortunately, that's not the case. Medicare does not cover assisted living, competent nursing, or long-term care.
If you're unable to leave your home for medical or therapeutic care, Medicare will pay for home healthcare services. Importantly, Medicare will not cover 24-hour care. Long-term Care (LTC) Insurance is created to cover long-lasting services and assistance not covered by traditional medical insurance or Medicare. It can include a variety of advantages for individuals who require continuous medical attention and/or custodial care with everyday activities like consuming, bathing, or movement in centers from assisted living to full-time, in- home custodial care to a private room in a nursing center.
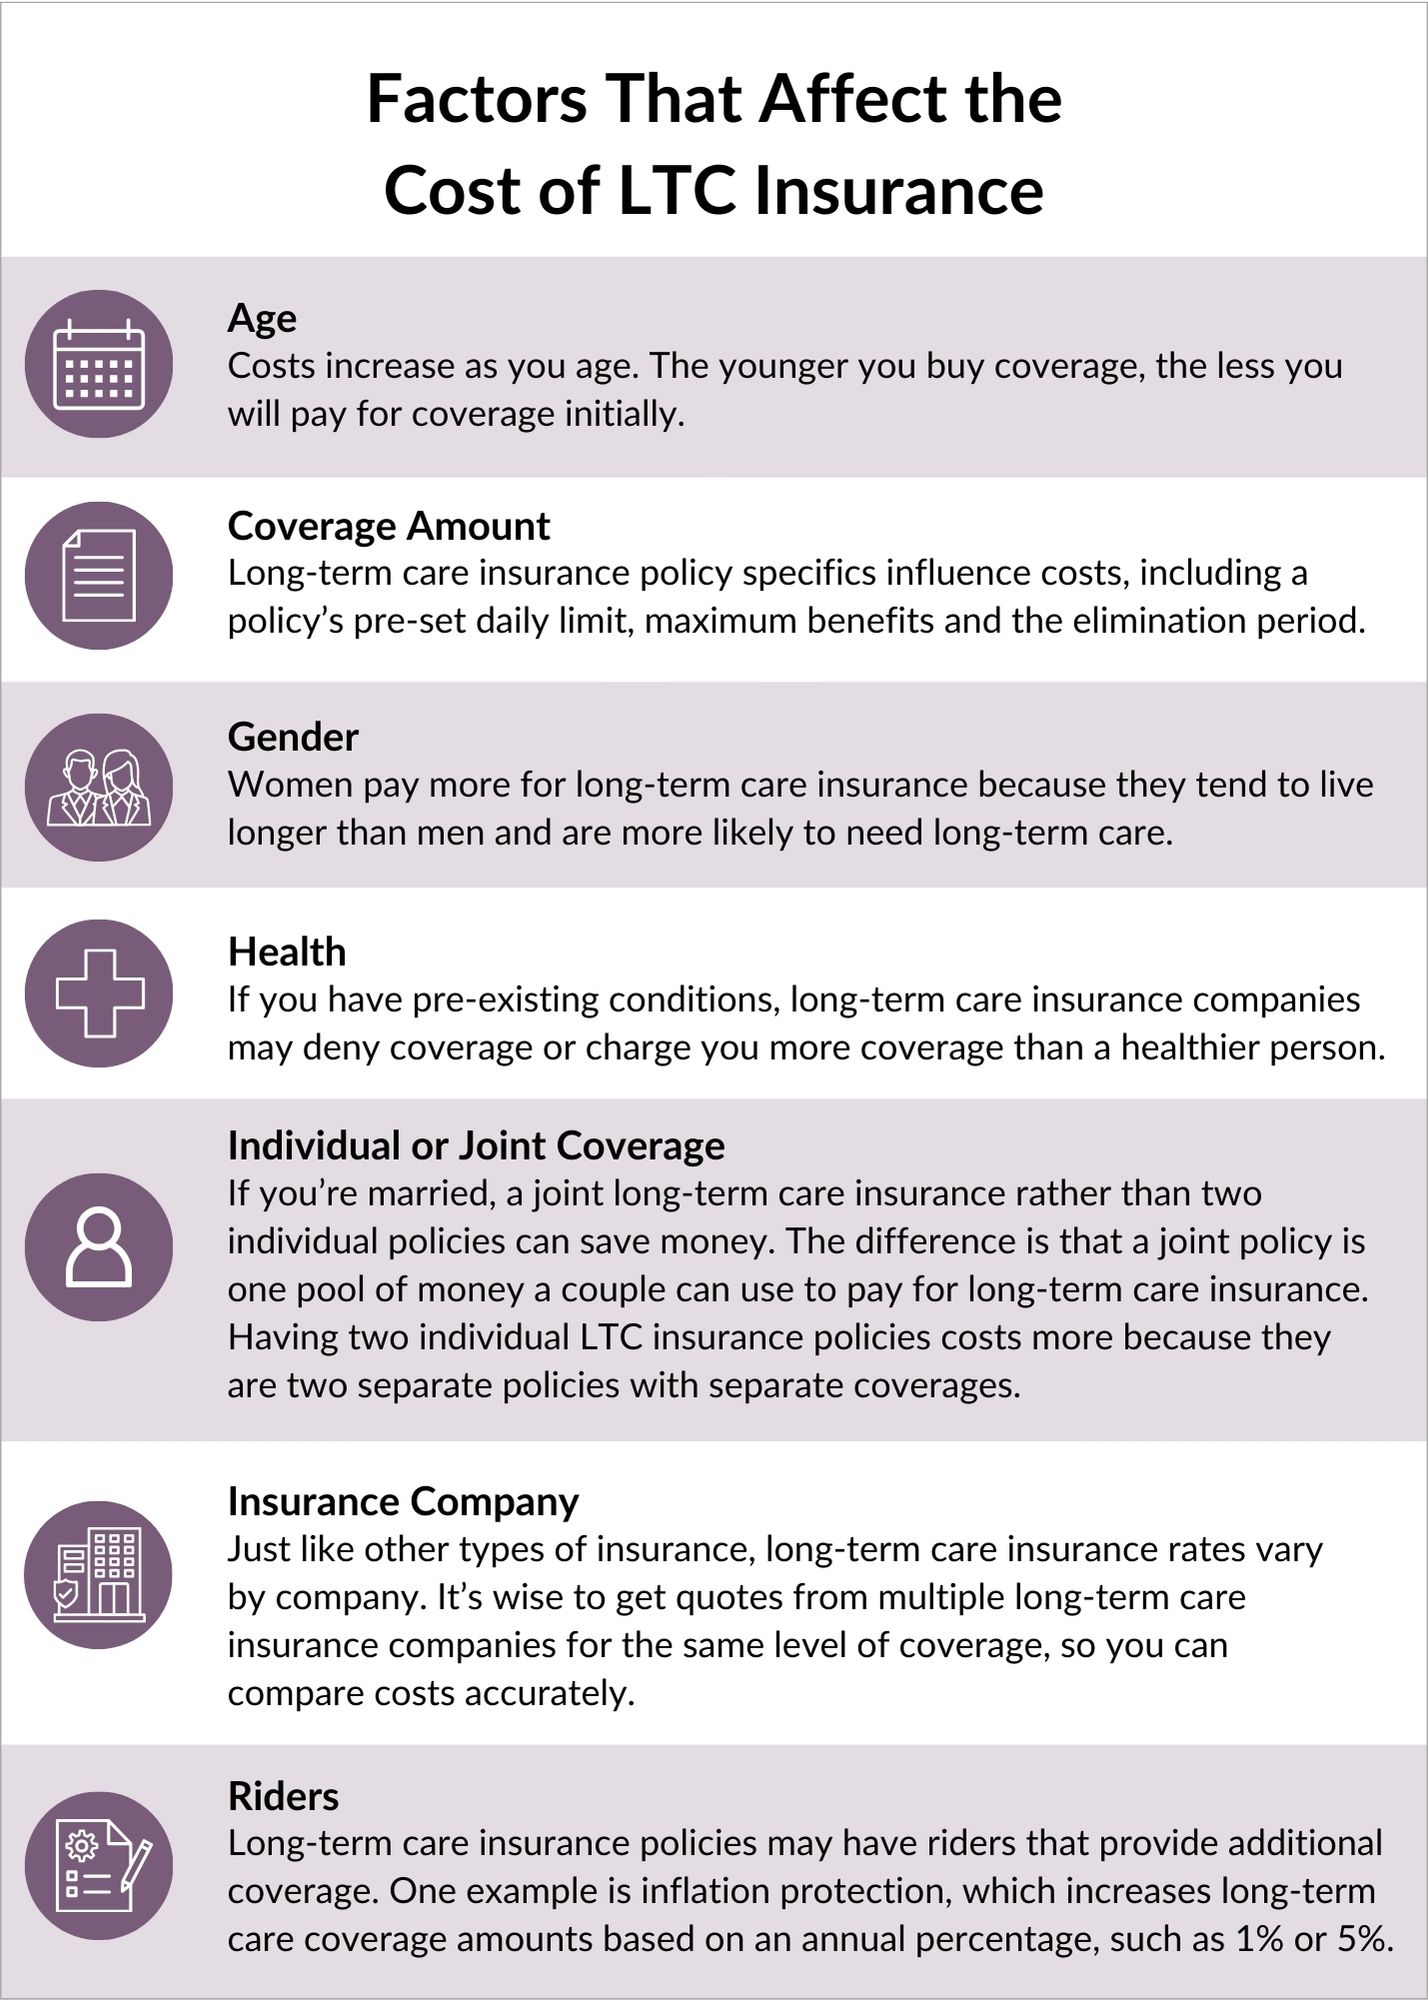
The cost of a long-lasting care policy is based upon age, wanted advantage amount and any additional advantages you choose to include. That's why it is essential to identify your long-lasting care needs and level of defense before it becomes an emergency situation. Thinking about long-term care is a foundation in any monetary plan, and there are numerous choices to choose from based on your monetary situation and needs.
Retirement Planning Huntington BeachKey Advantages of Senior Accident Insurance
It's much better to be overprepared and covered, than underprepared and economically devastated.
Medicare does not cover your long-term nursing care or 24/7 in-home services, nor does it spend for your custodial care that includes your daily activities such as eating, bathing, and dressing.

Why do lots of monetary advisors tell clients they can self-insure for long-lasting care but advise them to buy additional protection to Medicare? This question has actually plagued me for thirty years. The primary factor this subject is so important is that the most common objection my group and I encounter regarding long-lasting care insurance is, "I'm going to self-insure." Many individuals genuinely prefer the defense of insurance, yet their monetary consultant typically recommends that self-insurance is more effective.
They consistently buy Part D drug coverage, either combined with Medicare Benefit or a standard Medicare supplement. Financial consultants seldom recommend against buying supplemental Medicare coverage.
Evaluating the Right Annuity for Retirement
The average claim payment is considerably less than $4,000 annually, according to Telos Actuarial. For 2026, there is a $2,100 cap on drug coverage under Part D. If you don't think me that the claim payments are small, take a look at the Description of Benefits that reveals the claim payments from your Medicare Supplement or Part D drug plan.

Latest Posts

Managing Longevity and Long-Term Care Needs in 2026
Funding Future LTC Expenses
LTC Options Beyond Medicare