All Categories
Featured
Long-Term Care Options Beyond Medicare
Table of Contents
Long-lasting care (also called "custodial care" or "long-lasting services and assistance") includes medical and non-medical take care of individuals who have a chronic disease or special needs. Most long-lasting care assists with standard personal tasks of everyday life, often called "activities of day-to-day living." This includes things like: Help with personal care support (like dressing, bathing, and using the restroom)Home-delivered mealsAdult day health careTransportationIt's important to start planning for non-medical long-lasting care now to maintain your independence and ensure you get the care you might require, in the setting you want, now and in the future.
How can I discover long-term care choices if I'm presently in a medical facility or assisted living home?.
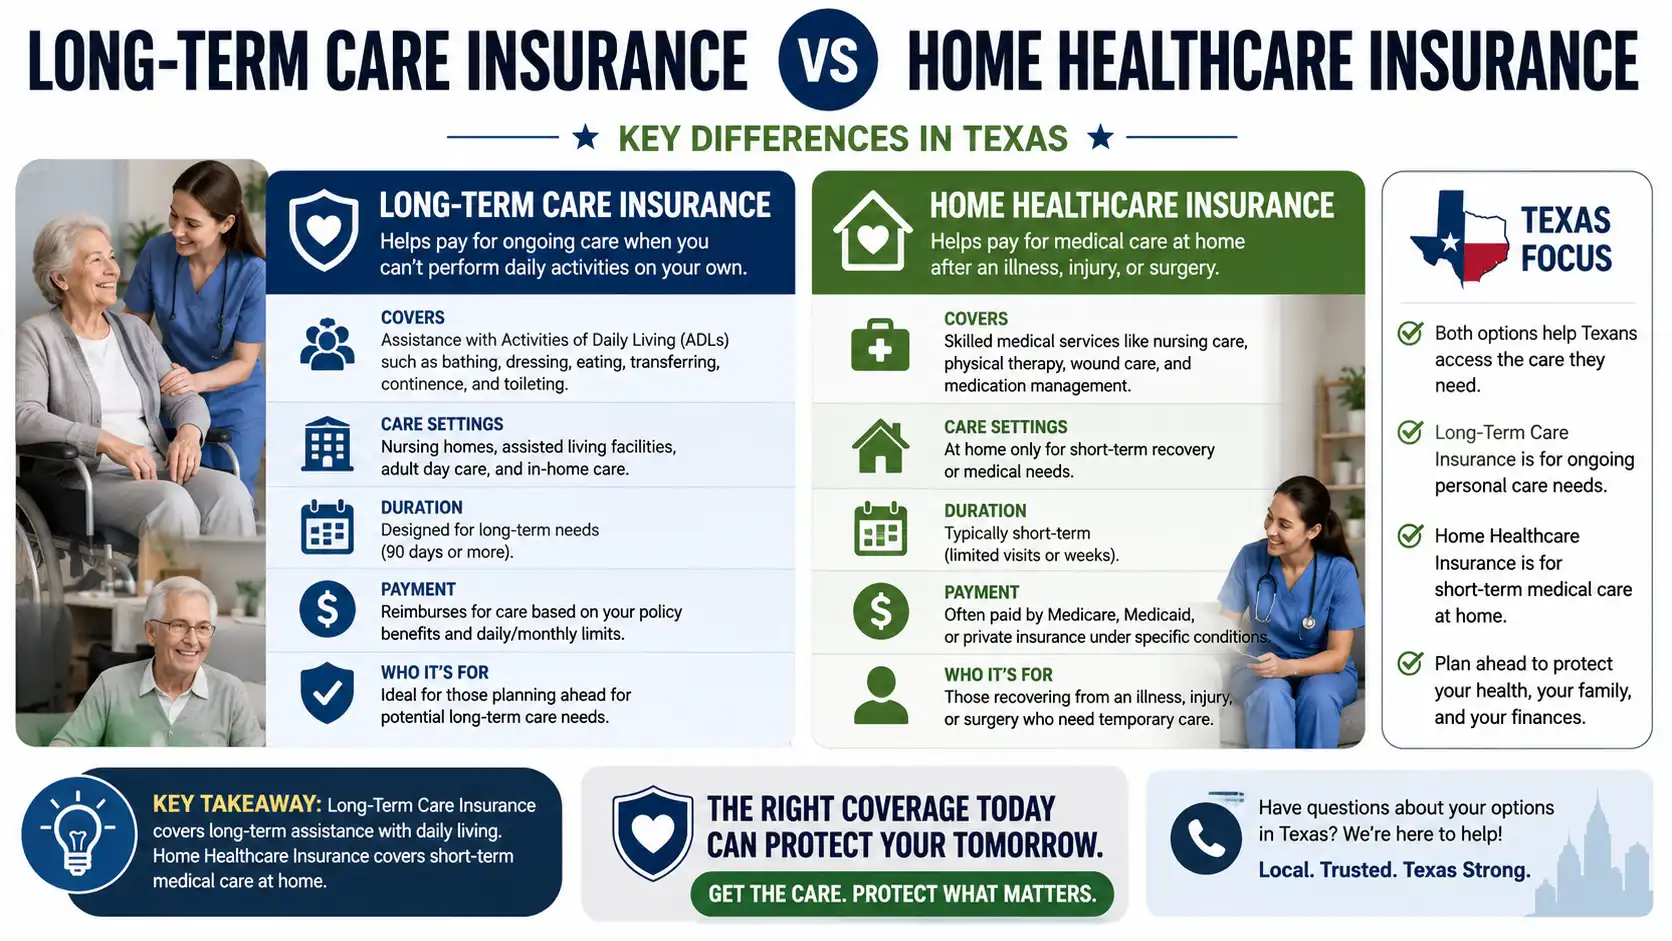
As you age, there might come a day when you require some extra help looking after yourself. Long-term care is the individual help you may require if you're unable to carry out the Activities of Daily Living, or ADLs, by yourself for a prolonged amount of time. The 6 ADLs include: Eating Bathing Dressing Transferring Toileting (to or from a bed or wheelchair) Continence When you hear "long-lasting care," you may immediately believe "assisted living home," but today there are a wide range of services readily available that you might receive at a facility, in the neighborhood or in the convenience of your own home.
Consider these typical day-to-day expenses of care:1 Housewife services: $163 daily Home health aide: $169 daily Helped living center: $148 each day Semi-private space in a nursing home: $260 daily Private space in a retirement home: $297 daily Most retired people can't manage to pay for long-lasting care by themselves, a lot of turn to long-lasting care insurance coverage.
Comparing LTC Insurance Versus Medicare
It can cover your expenses in a range of settings, from your own home to center locations, such as adult day care, a nursing home or retirement home. Long-term care policies usually repay you a financial daily quantity (as much as a preselected limitation) for assisted care services, such as eating, bathing or dressing.
Here are some main differences in between these protection types: is developed to cover acute care, or the care you need when you're sick and will eventually recover from your health problem. It covers physician visits, healthcare facility stays and rehabilitative care. Under this advantage, competent nursing care is just covered in full for 20 days and then partly for 21 to 100 days, with no protection after 100 days.
2 When it comes to Medicare protection for home health care, the key is whether the care is proficient or not. Medicare does not cover home health aide services (like bathing, dressing and utilizing the restroom) unless you're likewise getting proficient care such as nursing care or other treatment. Home health assistant services are never covered when that is the only care you require.
Variable and Fixed Annuities for Seniors
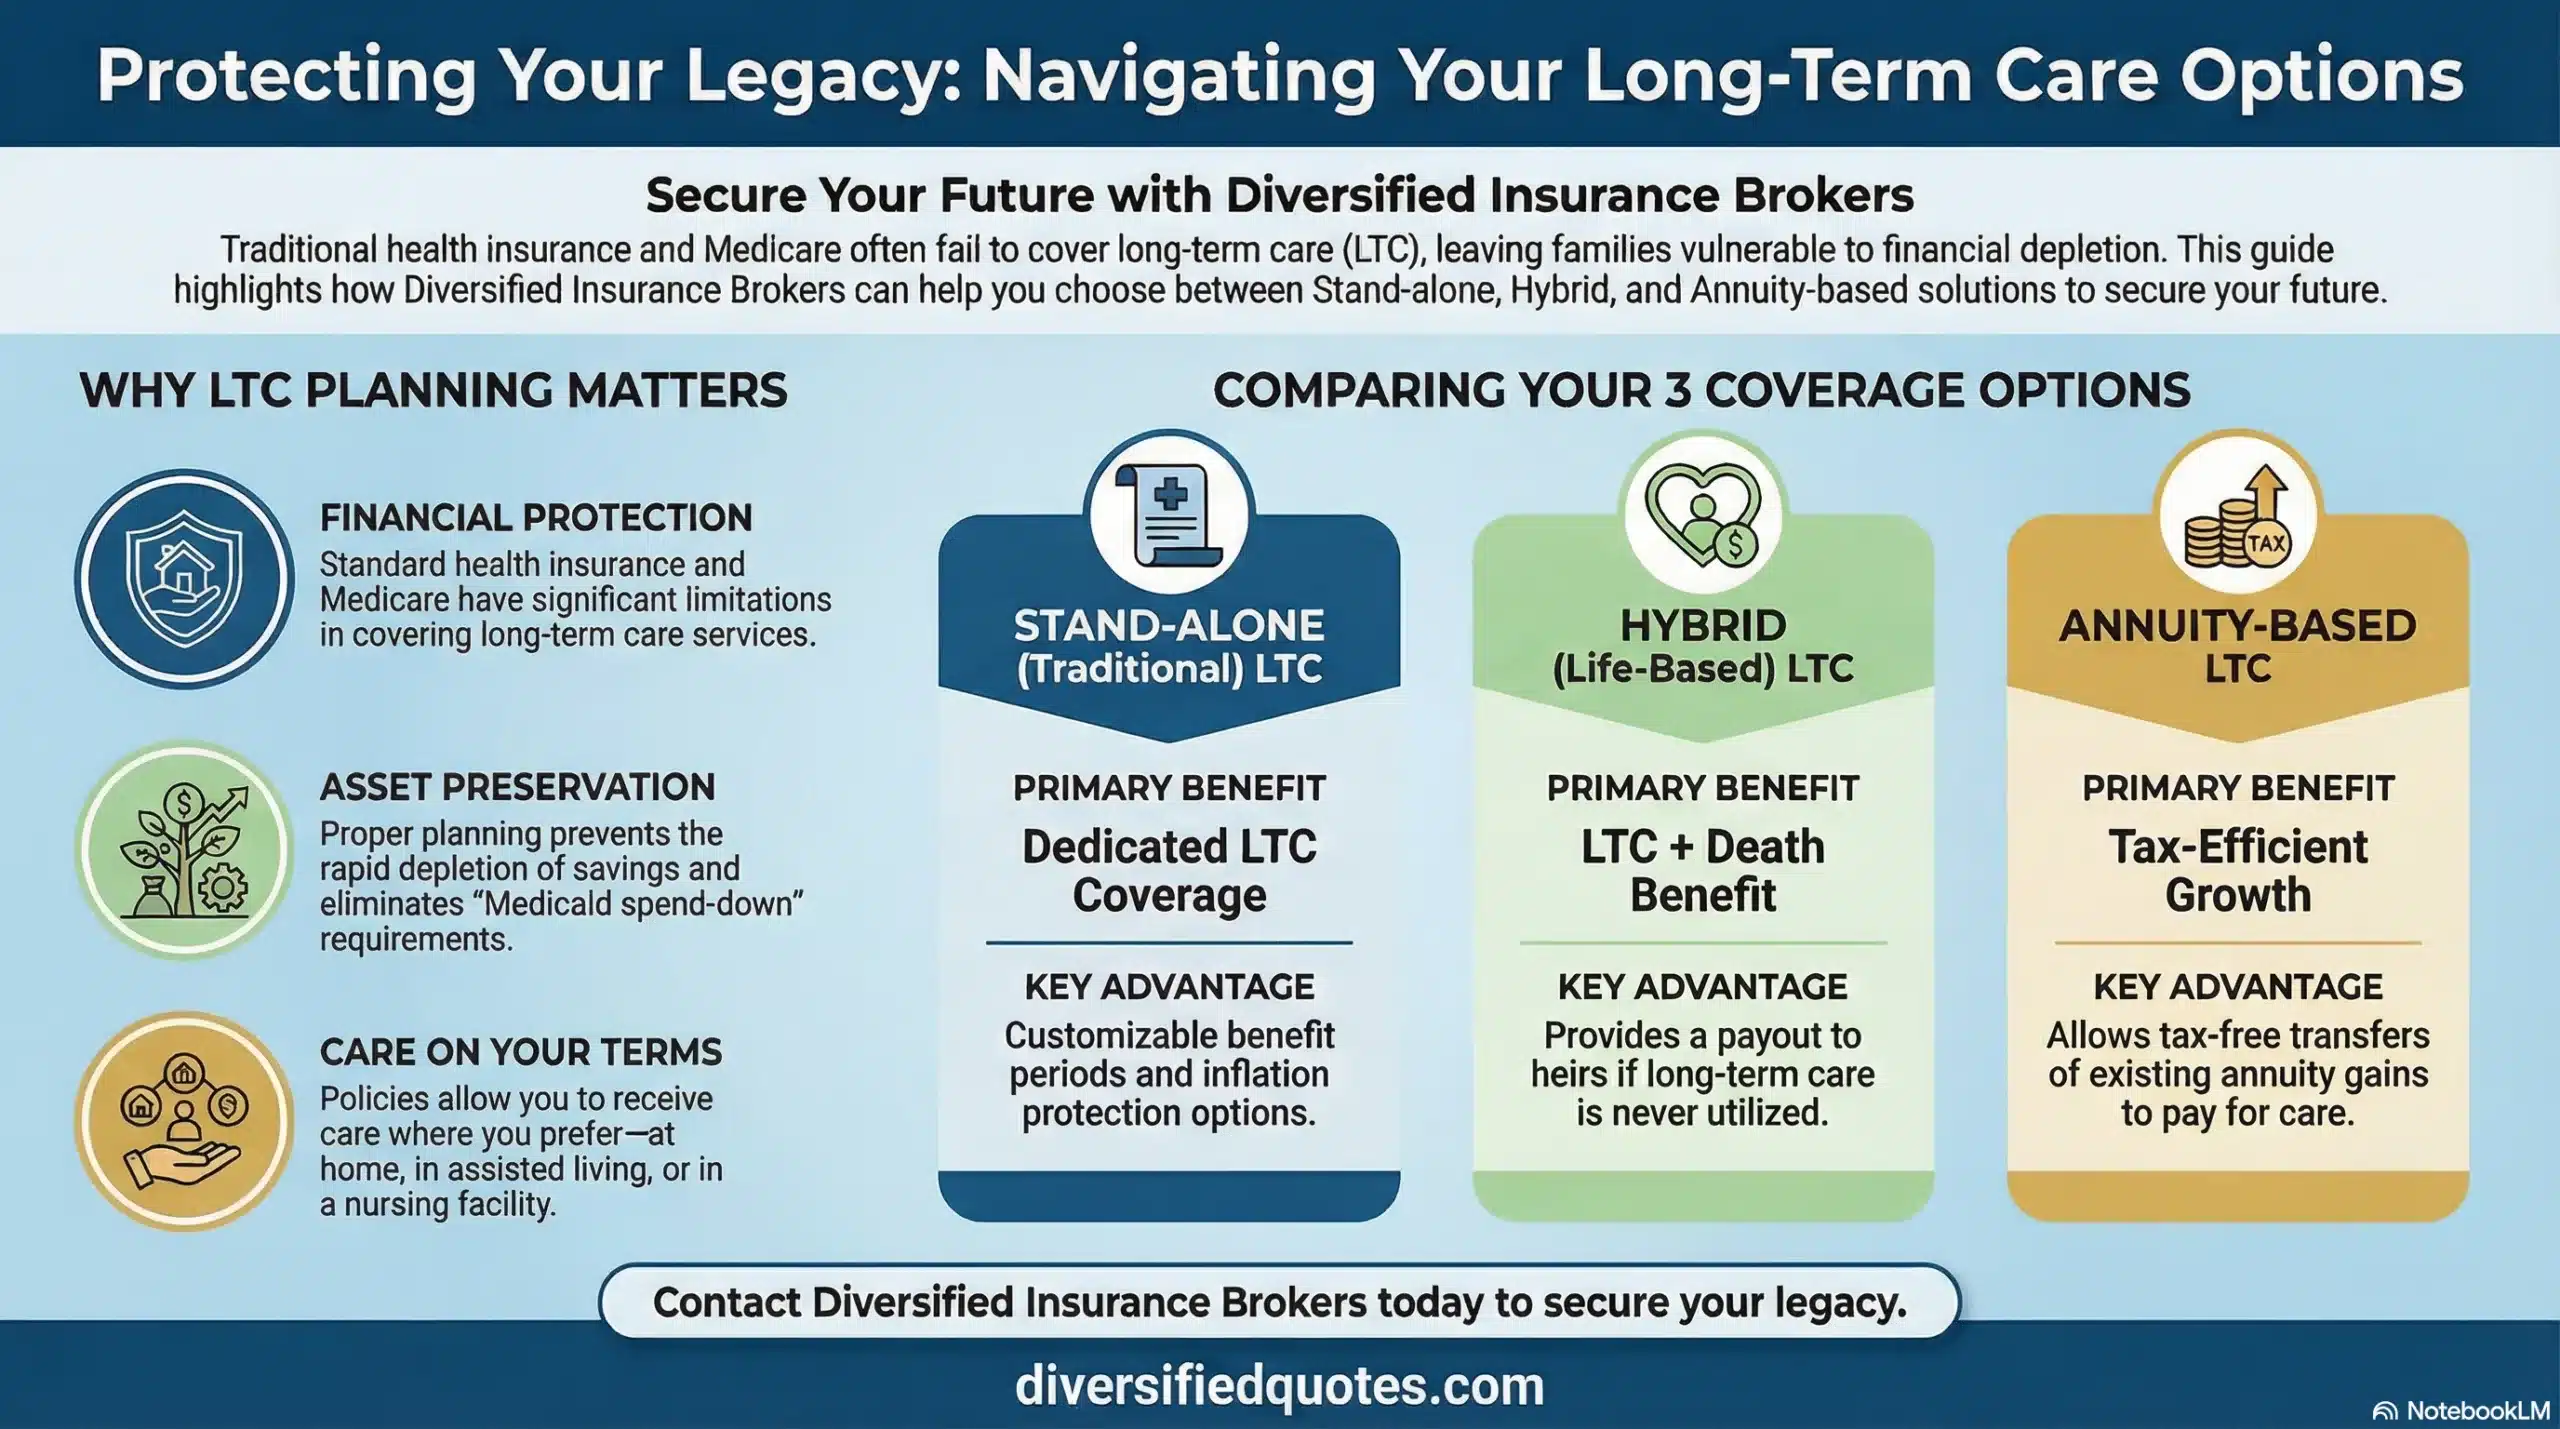
Long-term care insurance is specifically designed to assist pay the expense of long-lasting care services by providing coverage straight for facility and home health care. We recommend talking to a trusted consultant or an insurance representative that specializes in long-lasting care before making any insurance purchase. Bankers Life can assist you take the next action in preparing your long-term care strategy.
Nursing Home Costs in 2023, ,, Knowledgeable nursing facility (SNF) care, ,, Home health services, , 2023. Bankers Life and their licensed agents/producers are not linked with or backed by the U.S. government or the federal Medicare program. ICC23-210431.
You usually can't get covered long-lasting care with Medicare. So, does Medicare pay for any nursing home care? Outside of the medical care you need, it does not. But different parts of Medicare might assist with services like experienced nursing care. Medicare Part A offers health center insurance coverage. This normally has absolutely nothing to do with nursing home care.
Medicare Part B deals medical insurance. This generally indicates preventive care, which you could get in a retirement home setting. But Part B doesn't cover the stay itself unless it's a medically required short-term stay. A long-lasting stay with custodial care would not be covered. Medicare Benefit (Part C) offers all the coverage you obtain from Components A and B.
Retirement Planning San Diego CALike Part A and Part B, Medicare Benefit does not generally cover custodial care. You can get an Institutional Unique Needs Strategy (I-SNP) that might provide this protection. Medicare Part D offers prescription drug coverage. If you require a covered prescription drug while staying in a retirement home, Part D will help spend for it.

Latest Posts

Managing Longevity and Long-Term Care Needs in 2026
Funding Future LTC Expenses
LTC Options Beyond Medicare