All Categories
Featured

Strategic Income Options for Older Americans
After all, as the saying goes: "Buyer beware!" This article is prepared by Pekin Hardy Strauss, Inc. ("Pekin Hardy," dba Pekin Hardy Strauss Wealth Management) for informational purposes only and is not planned as a deal or solicitation for company. The information and data in this article does not make up legal, tax, accounting, investment, or other expert advice.
Reverse Mortgage Life InsurancePekin Hardy can not ensure that the strategies discussed herein will outshine any other investment method in the future.
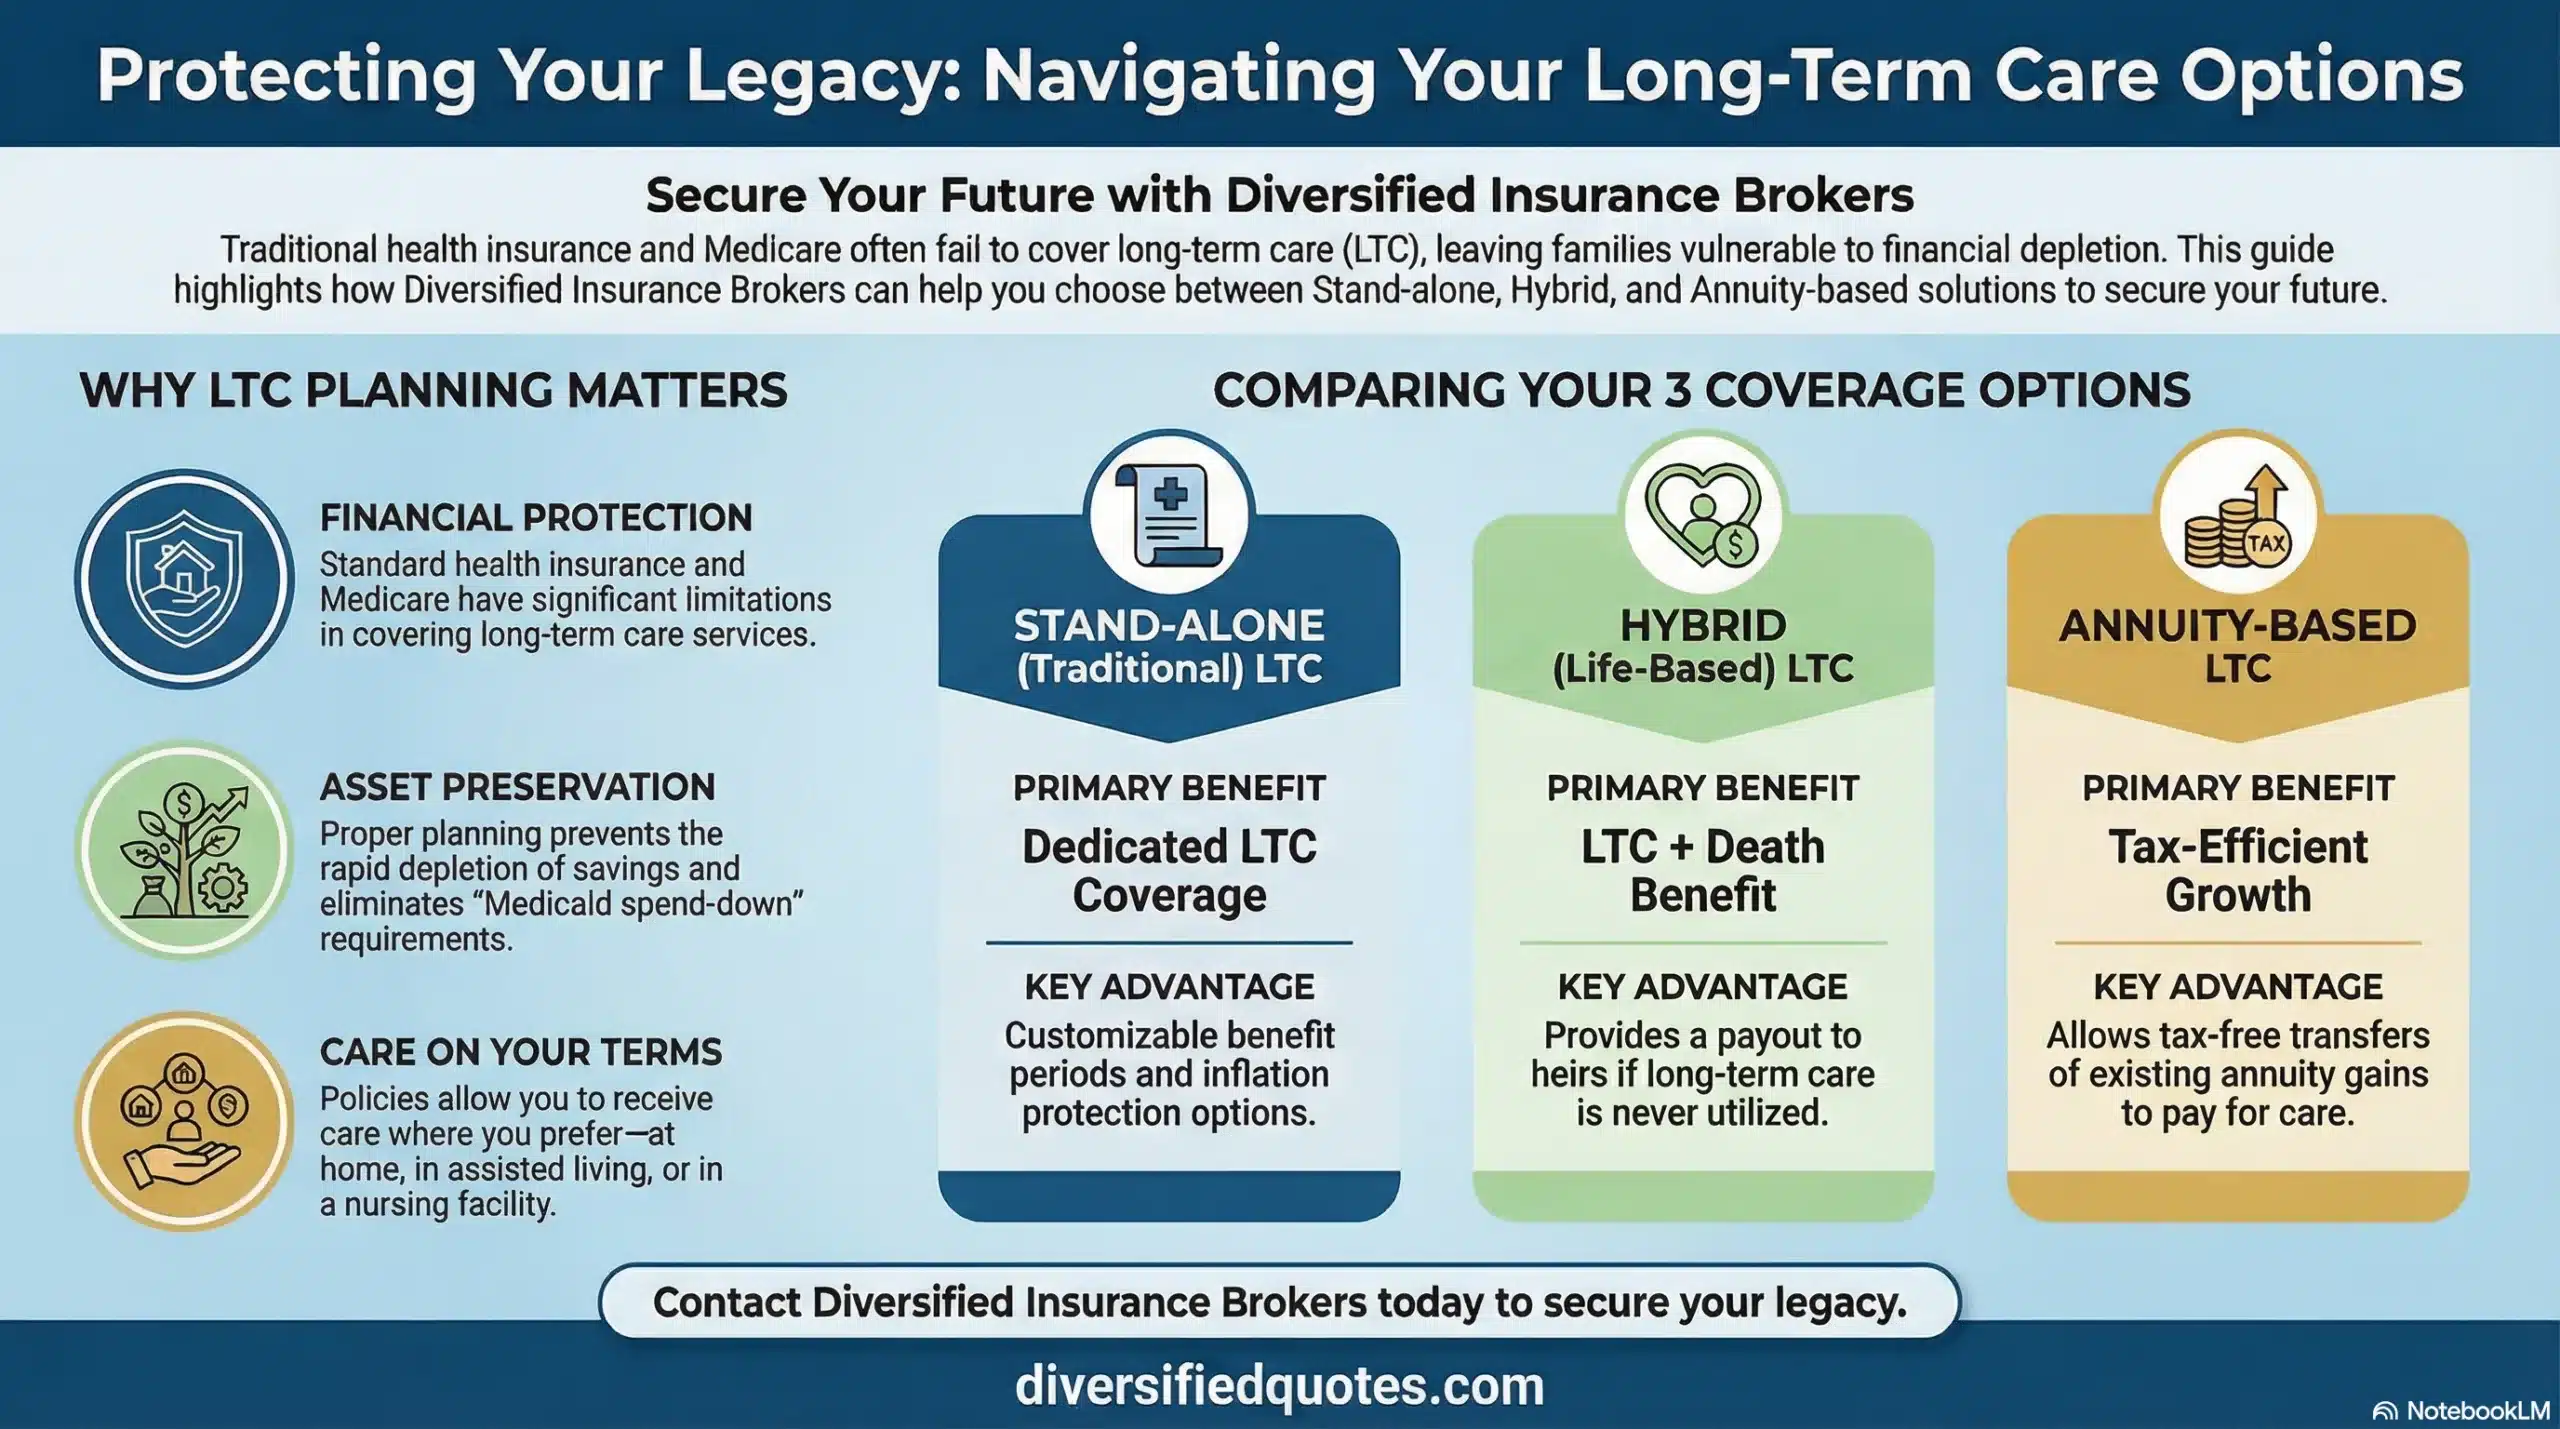
A set annuity is a tax-efficient retirement savings option that can assist develop predictable assets while you're working. After you choose to retire, it can develop an ensured stream of income that could last for the rest of your life. Check out to learn more about: A set annuity is a contract with a life insurance coverage company that is comparable in many ways to a bank certificate of deposit.
Generally, the rate of return is ensured for several years at a time (for instance, 3 or 5 years). After the initial guaranteed duration, the insurance company will reset the interest rate at routine intervals usually every year but the new rate can not be lower than the ensured minimum rates of interest in the agreement.
When you choose to take income in retirement, the insurance provider uses those funds to make regular payments to you for the period of time defined in the annuity contract (e.g., 10 or 20 years), or forever, for the rest of your life time. A set annuity (likewise called a fixed deferred annuity) starts as a cost savings automobile, and you can make contributions either as a lump-sum payment or as a series of contributions.
Expected Rising Rates for 2026
This amount of time before you start taking earnings is known as the build-up stage. The circulation (or payout) stage begins when you choose to begin making withdrawals, normally at retirement (and there can be tax effects to withdrawing funds from an annuity before age 59). If you purchased the annuity with pre-tax dollars, withdrawals will generally be taxed as ordinary earnings but if you are retired or working less at that point, you'll likely be in a lower tax bracket.
You don't necessarily have to transform a repaired annuity into routine income payments in retirement. You can pick not to annuitize and receive the whole worth of the annuity in one lump-sum payment. Nevertheless, fixed annuities are typically bought to supply guaranteed income payments in retirement, which can be structured in various ways.
If you pass away during that duration, payments continue to your beneficiary. Single life: This option can ensure life time earnings by supplying routine guaranteed earnings payments for as long as you are alive. Once you pass away, the payments stop, regardless of the remaining balance in your annuity account.
After one individual dies, the enduring spouse continues to get payments up until they die. Regular payments in these annuities are normally lower than for a single life annuity because the insurer will likely have to continue paying income for a longer duration of time. There are many reasons that people choose these annuities, consisting of: Reliability: In addition to the guaranteed set rates of interest, your principal (the money you paid to buy the annuity) will remain undamaged unless you withdraw or decide to end the contract early.
Benefits of Senior Accident Protection Plans
This can be particularly helpful if you're currently in a higher tax bracket, then start to make withdrawals later in life when you remain in a lower tax bracket. Intensified growth: All interest that stays in the annuity also makes interest. This is called "substance" interest. This growth can continue for as long as you hold your annuity (subject to age limitations). Surefire income: After the first year, you can convert the amount in the annuity into an ensured stream of fixed earnings for a given duration of time or perhaps for the rest of your life if you choose.
Once your annuity payments have actually begun, there is no versatility to make changes. While fixed annuities can use stability and predictable income, there are potential downsides to think about.
Inflation threat: The set income from an annuity may not stay up to date with inflation, potentially wearing down purchasing power with time. Liquidity concerns: Early withdrawal from an annuity can feature significant penalties and give up charges, reducing access to funds for unforeseen requirements. There are numerous annuity types, consisting of repaired, repaired index, signed up index-linked (RILA), and variable.

Latest Posts

Managing Longevity and Long-Term Care Needs in 2026
Funding Future LTC Expenses
LTC Options Beyond Medicare